The loss
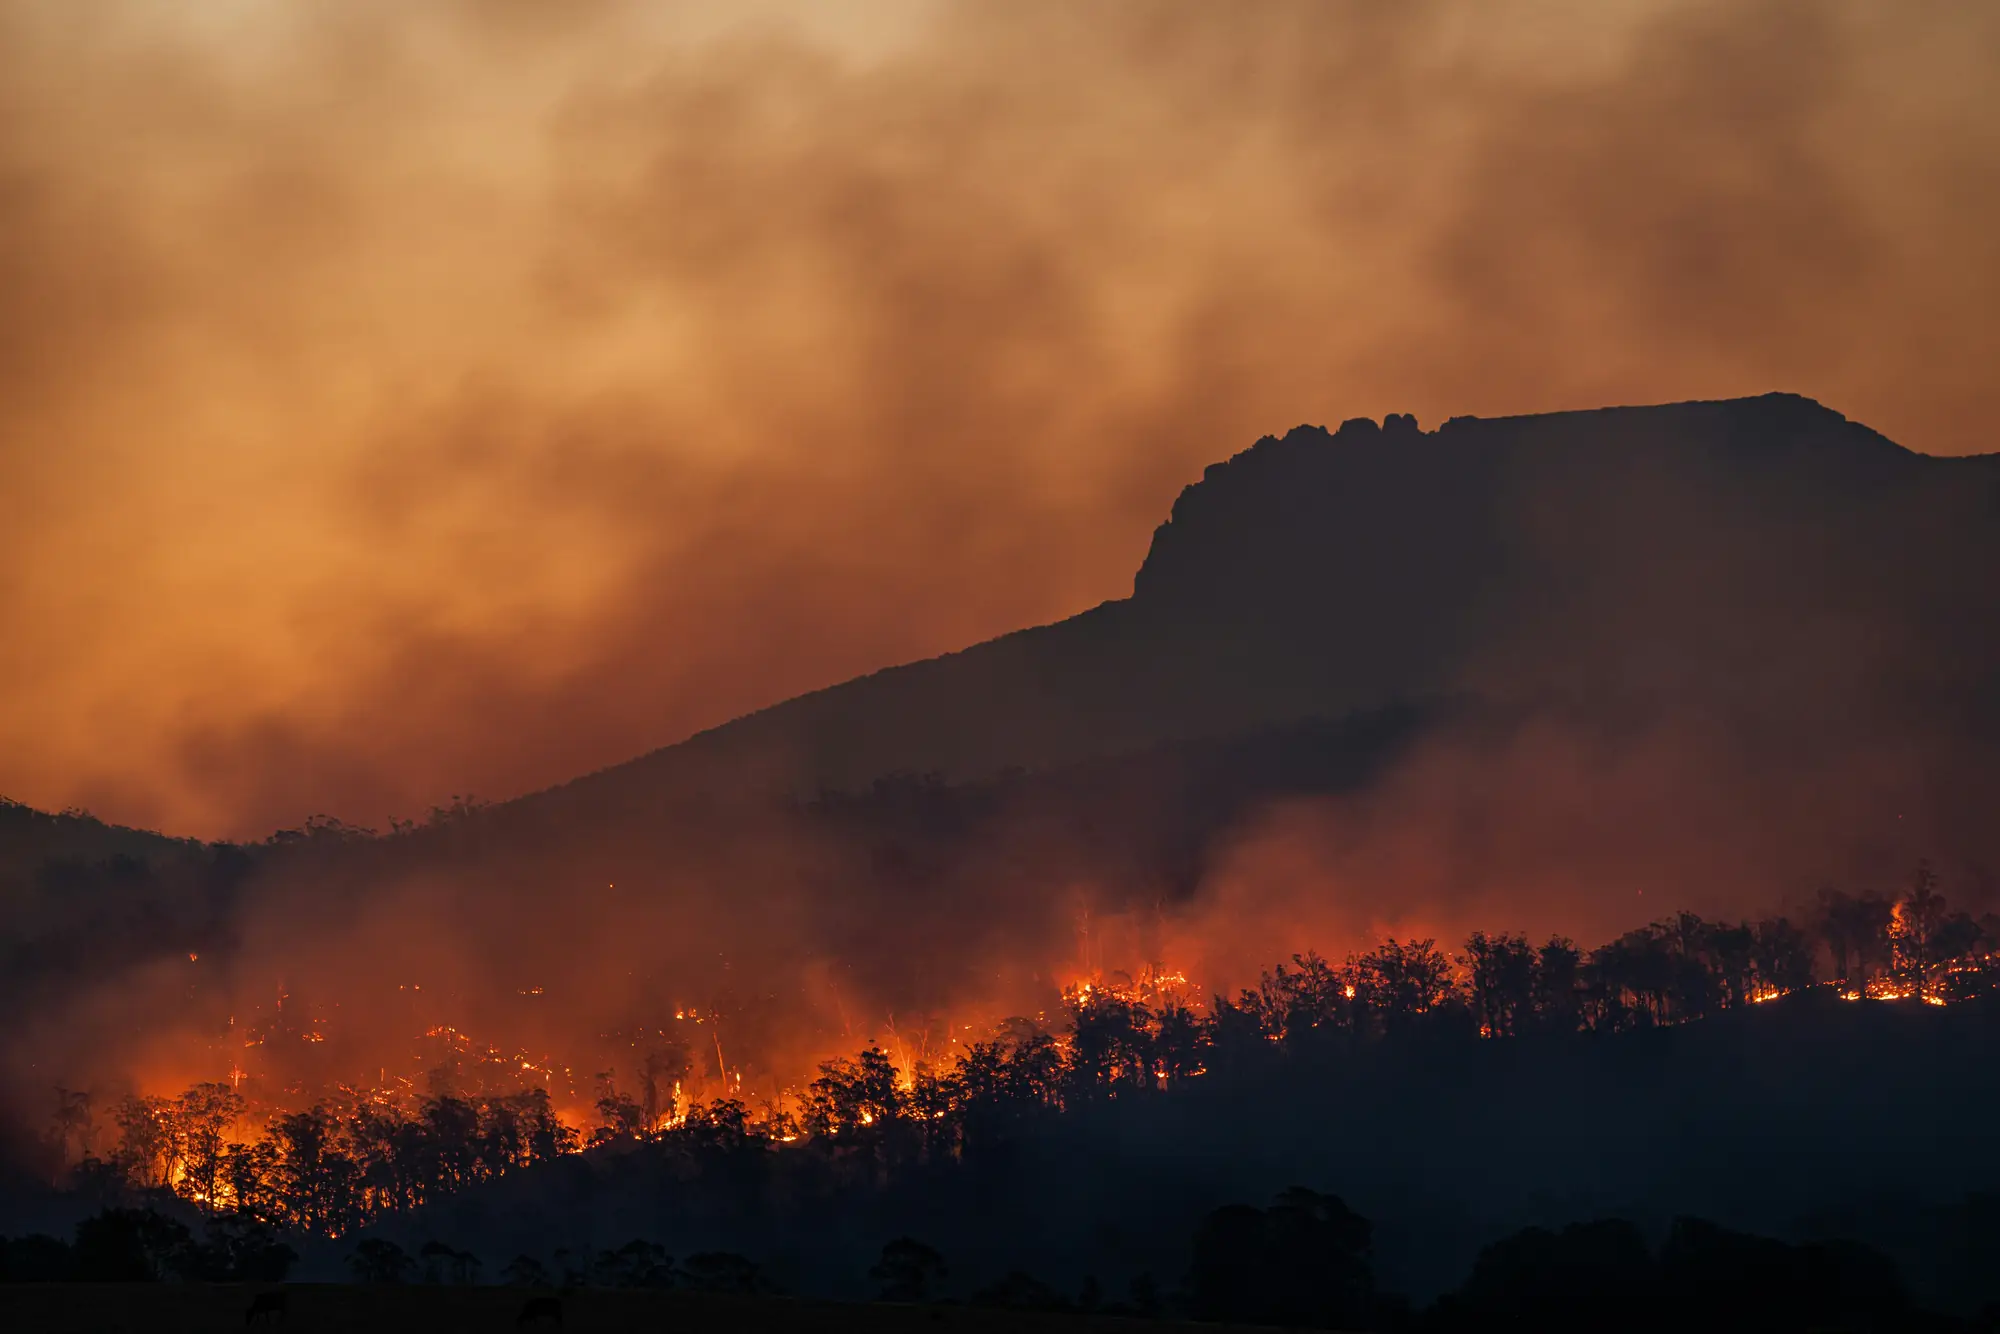
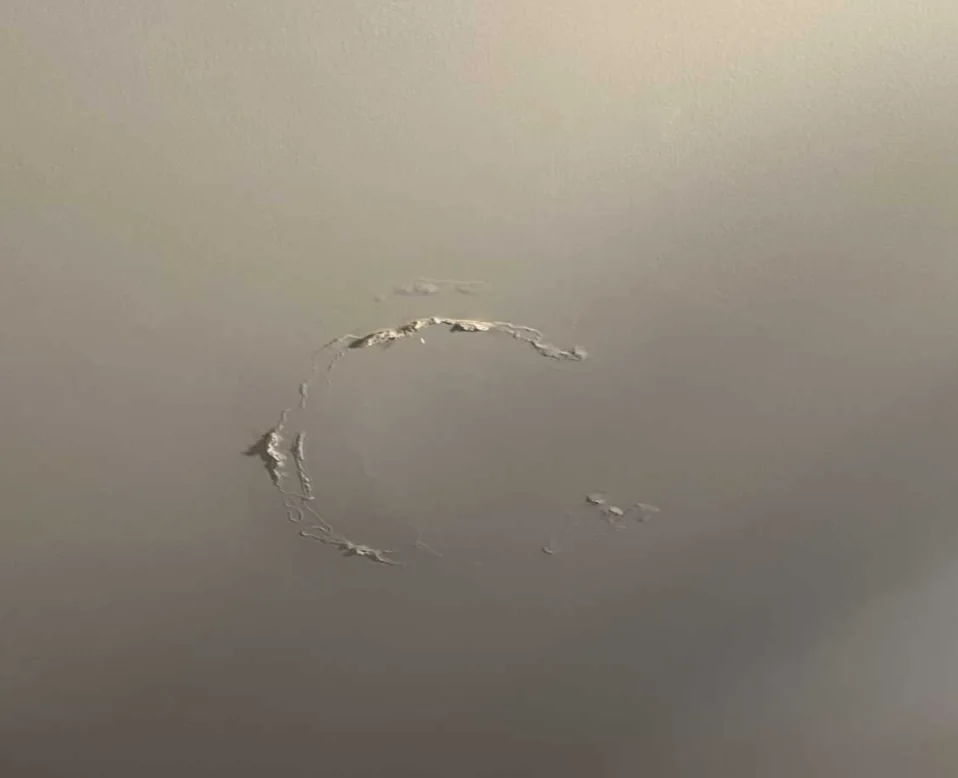
On March 14, 2024, wind damaged the roof of this Shadow Hills home. Shingles were lifted and displaced, the edge of the roof was left exposed, and water got into the house through the openings. Inside, the ceiling started to show it.
This is what makes wind driven water damage tricky to claim. The roof damage and the water damage inside have to be tied together, and insurance companies often try to treat them as separate problems or shrink the roof side down to a small repair.
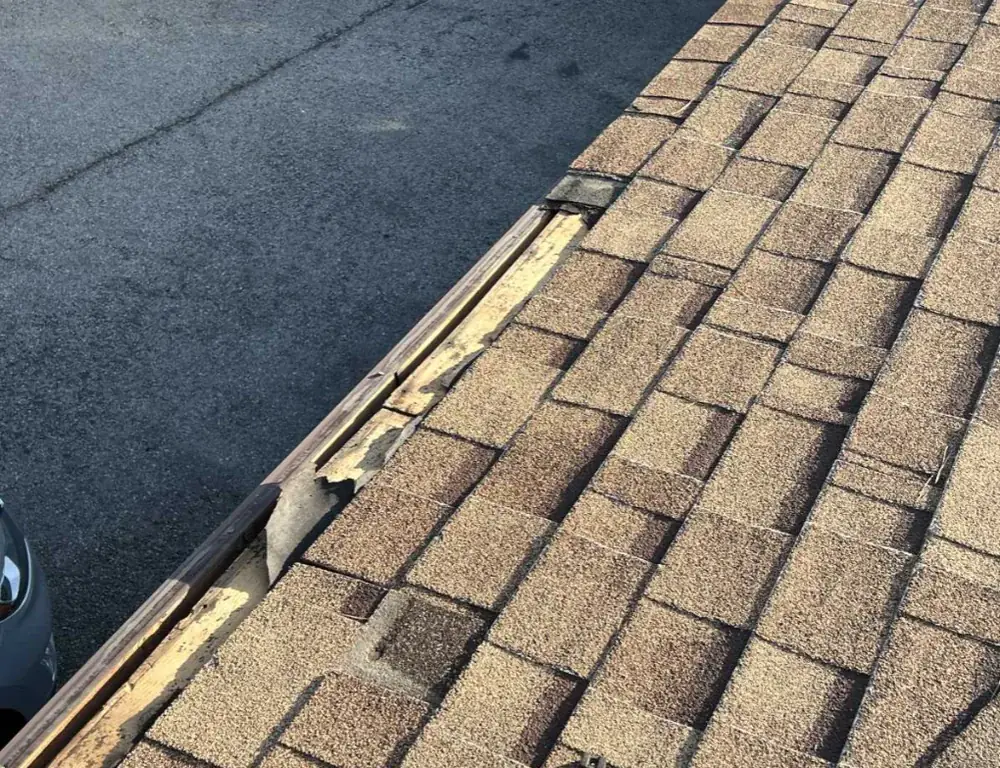
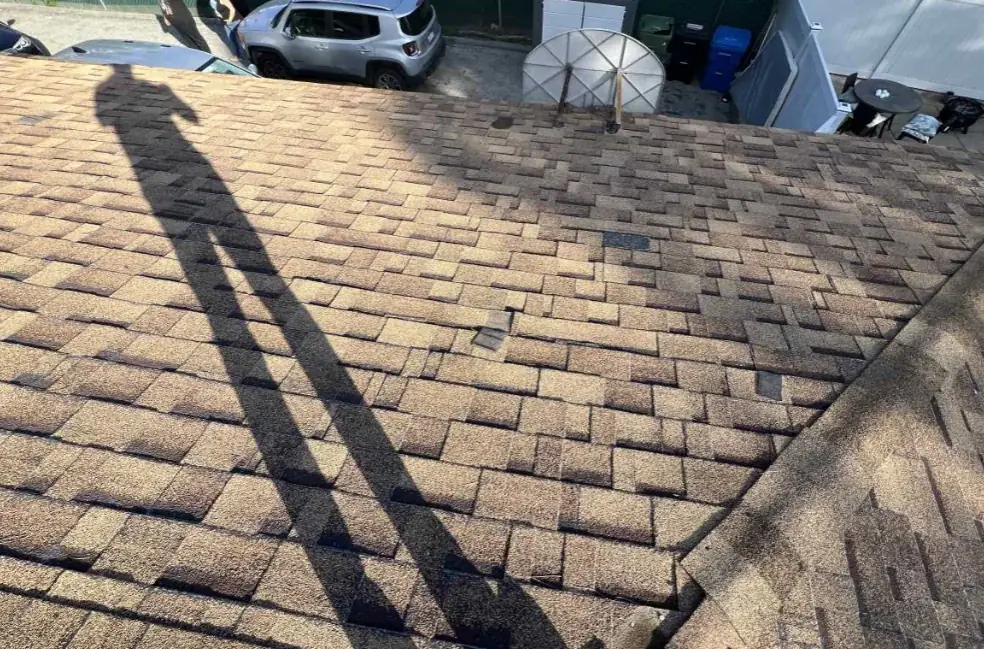
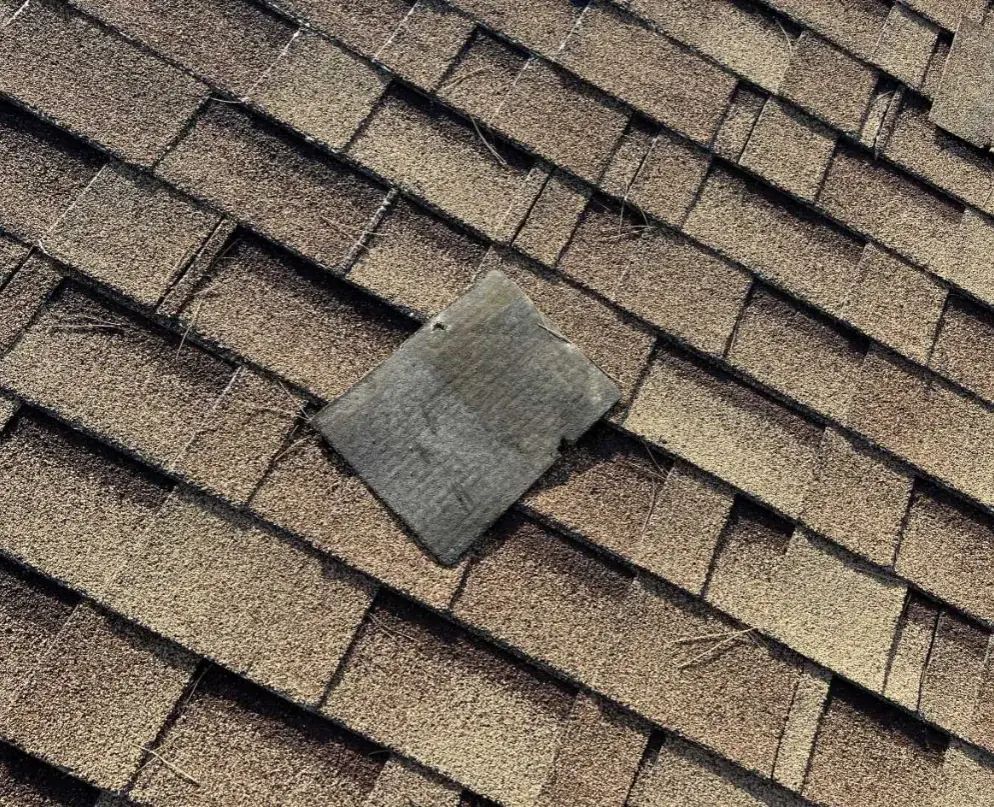
Water inside the home
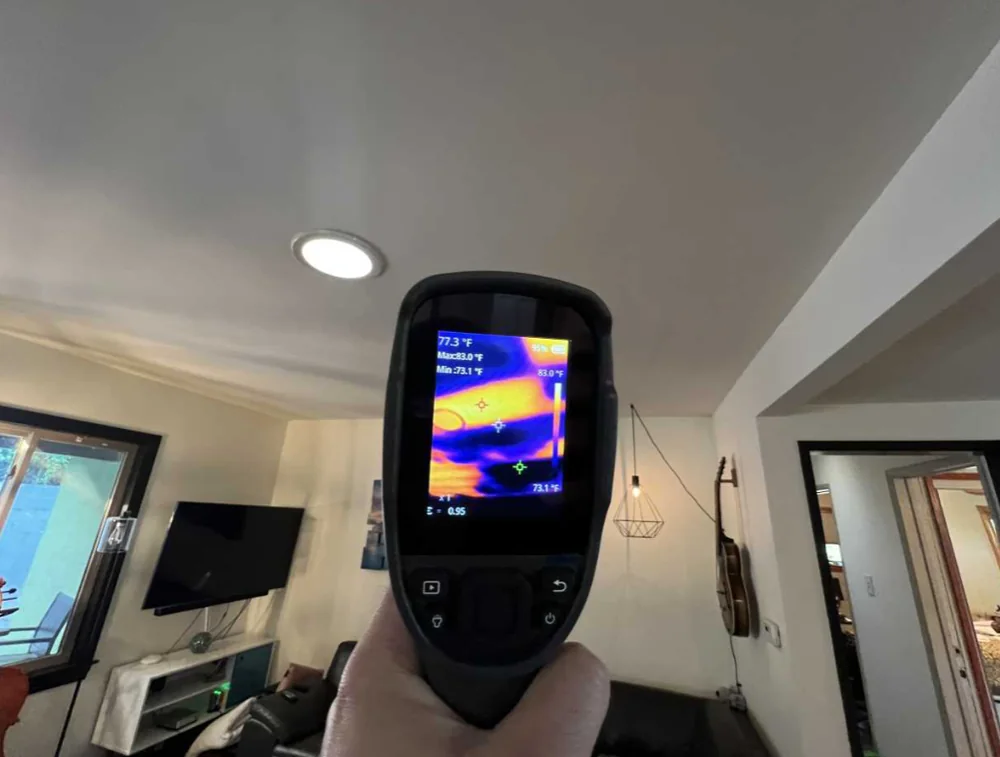
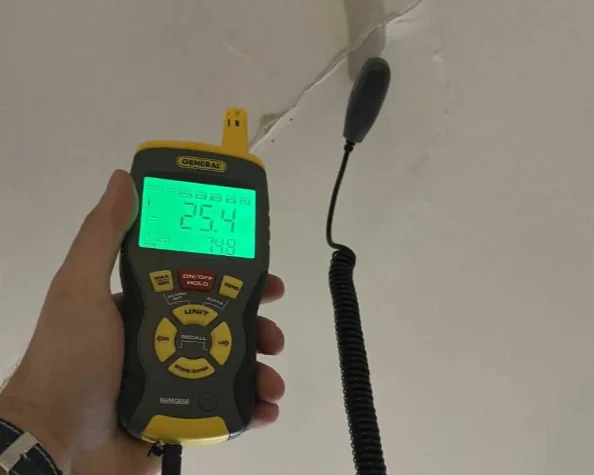
Water had worked its way into the ceiling, leaving peeling paint and moisture in the materials above. We used thermal imaging and a moisture meter to find where the water had gone and to put it on record, so the interior damage could be connected directly to the damaged roof.
Repairs on some slopes only
The carrier agreed the roof was damaged, but it only wanted to pay for repairs, and only on certain elevations. Elevations are the individual sides or slopes of the roof. In the carrier's view, the other slopes could stay as they were.
A roof works as one system. When some slopes are repaired and others are not, the home ends up with mismatched shingles, extra seams and transitions, and older material sitting right next to new, which are the places where leaks tend to come back. California's claim handling regulations also expect an insurer to correct a mismatch in the damaged area so the result has a reasonably uniform appearance.
We documented the condition of the roof as a whole instead of just the slopes the carrier had picked, and made the case that a patch job would not put the home back to its condition before the loss.
Pushback, then appraisal
The carrier did not move. Payments went out at different points along the way, but its position on the roof stayed the same and the claim dragged on for close to a year.
With negotiations stuck, we invoked the appraisal clause in the policy. Appraisal is the process most property policies include for settling disagreements over the amount of a loss. Each side names an appraiser, and an umpire steps in if the two cannot agree.
Appraisal gave us what the back and forth had not. The entire roof was included, not just the slopes the carrier first offered to repair.
The result
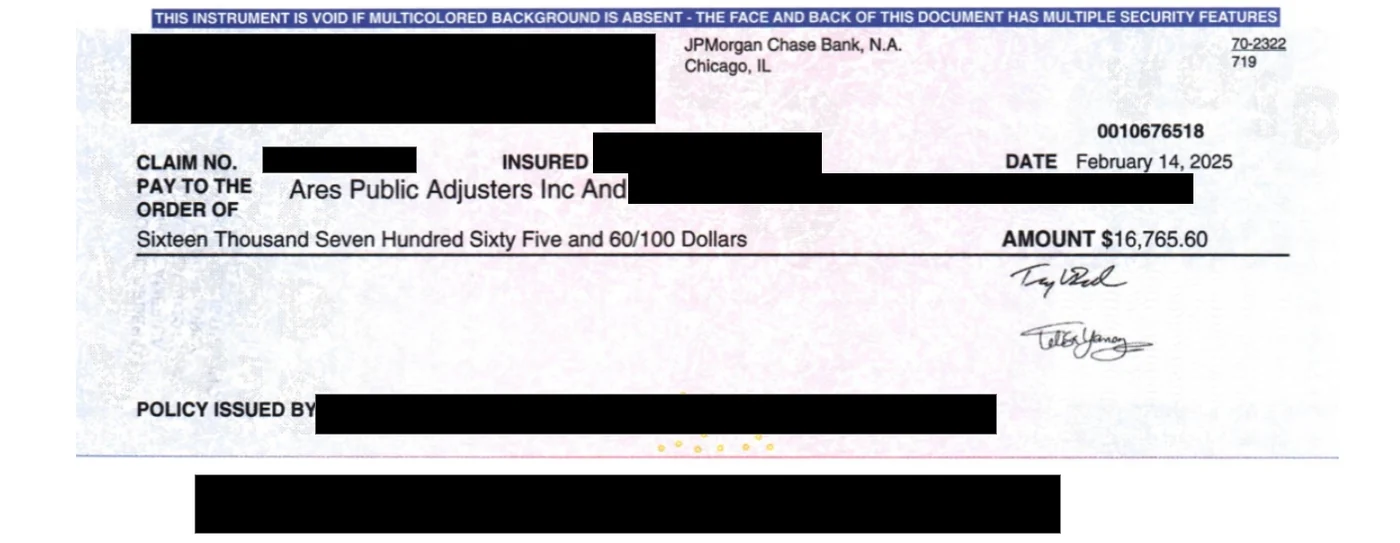
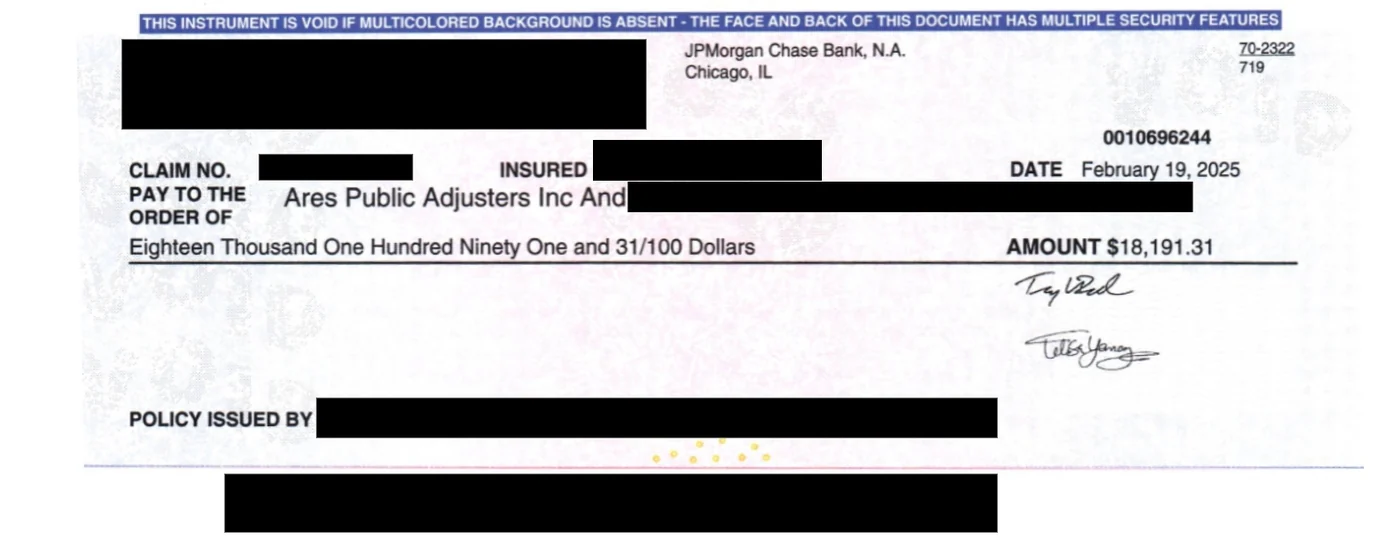
The final payments came in February 2025, close to a year after the loss, and the homeowner ended up with the full roof replacement instead of a partial repair. Payments on the claim totaled $69,242.64.
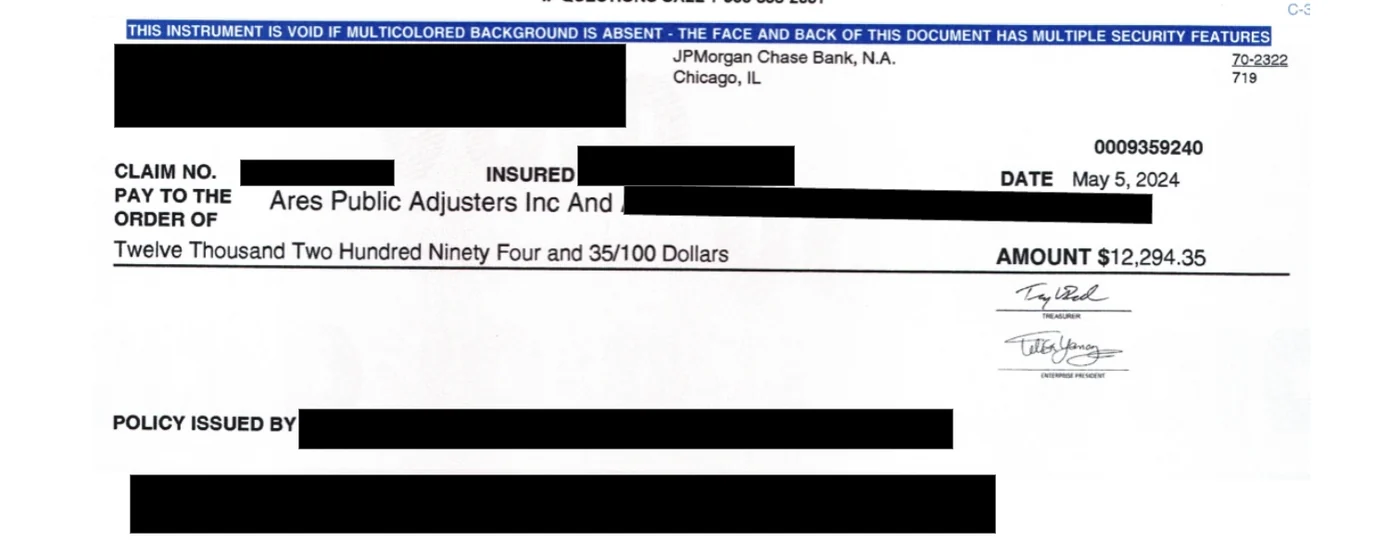
| Initial Rebuild Check | $12,294.35 |
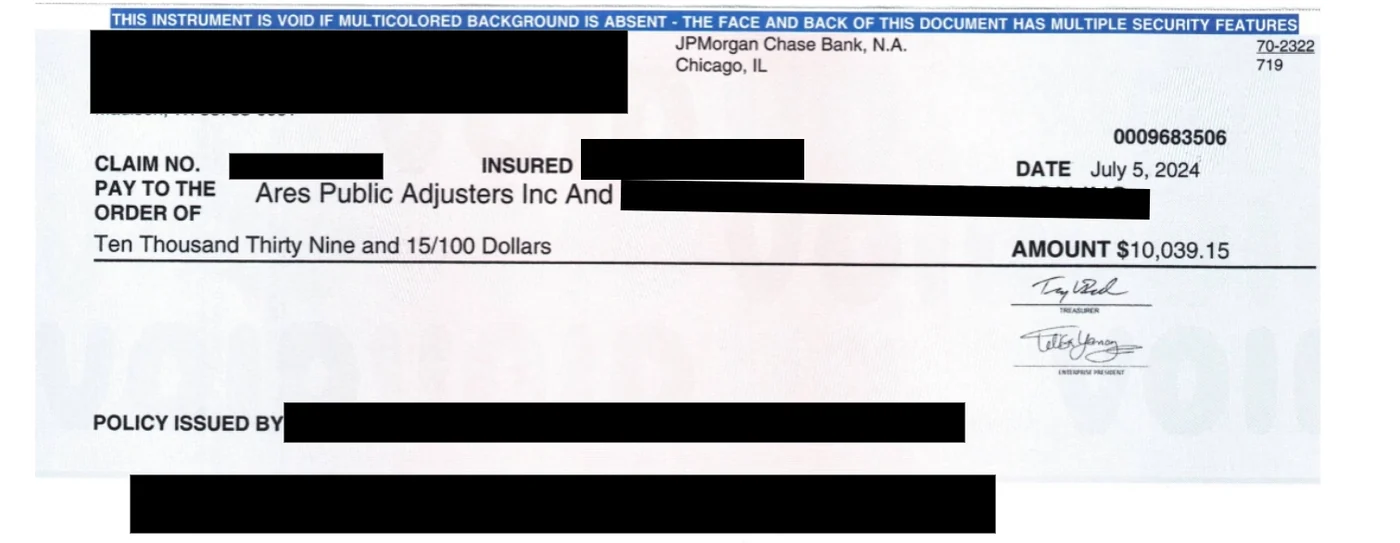
| Packout/Packback Check | $10,039.15 |
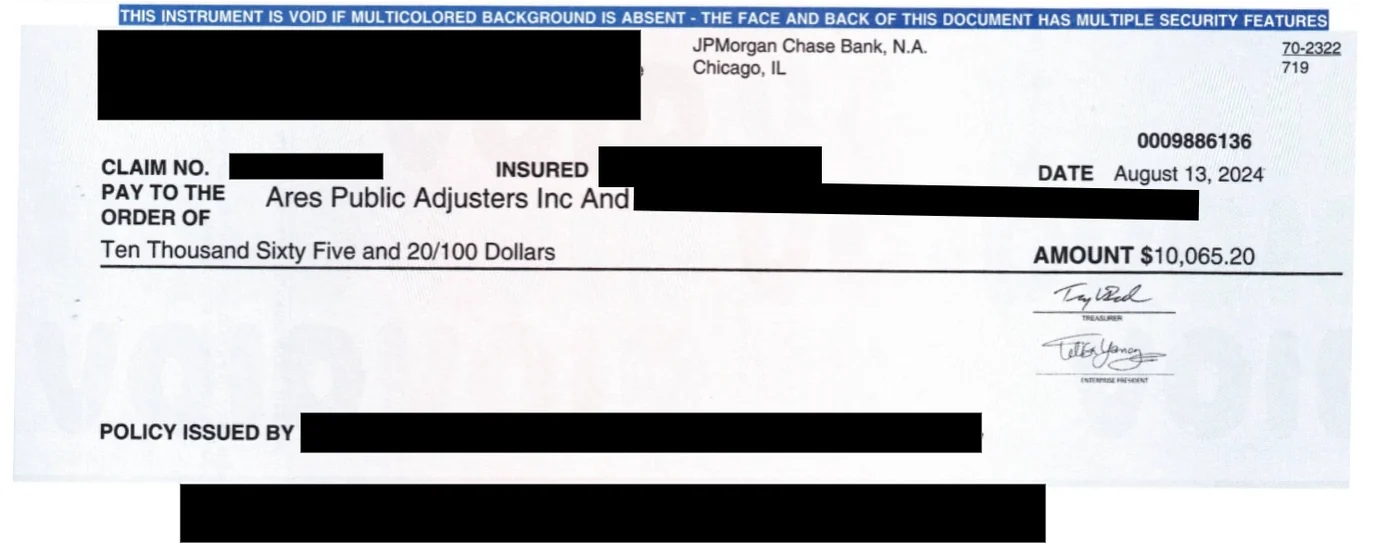
| Rebuild Supplement Check | $10,065.20 |
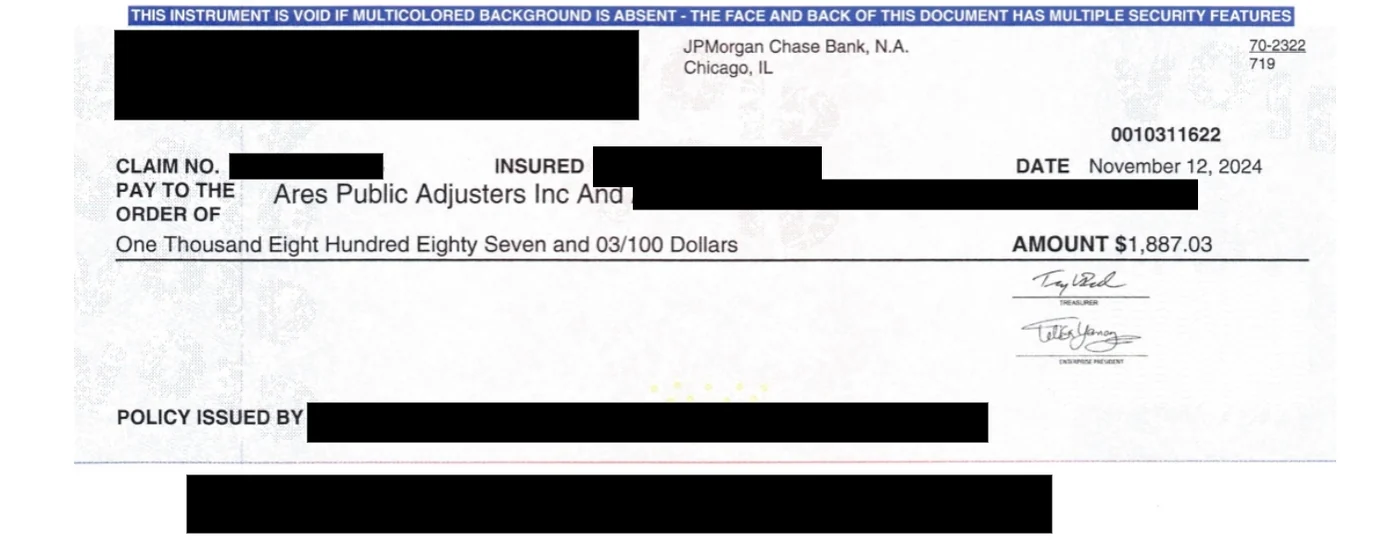
| EMS Supplement Check | $1,887.03 |
| Roof Replacement Supplement Check | $16,765.60 |
| Final Appraisal Roof Replacement Check | $18,191.31 |
| Total settlement | $69,242.64 |
If your carrier is offering to repair only part of your roof, you may have more options than you think. A free review can show you whether the scope makes sense.
Every claim is different and no result is guaranteed.
Settlement checks