The problem
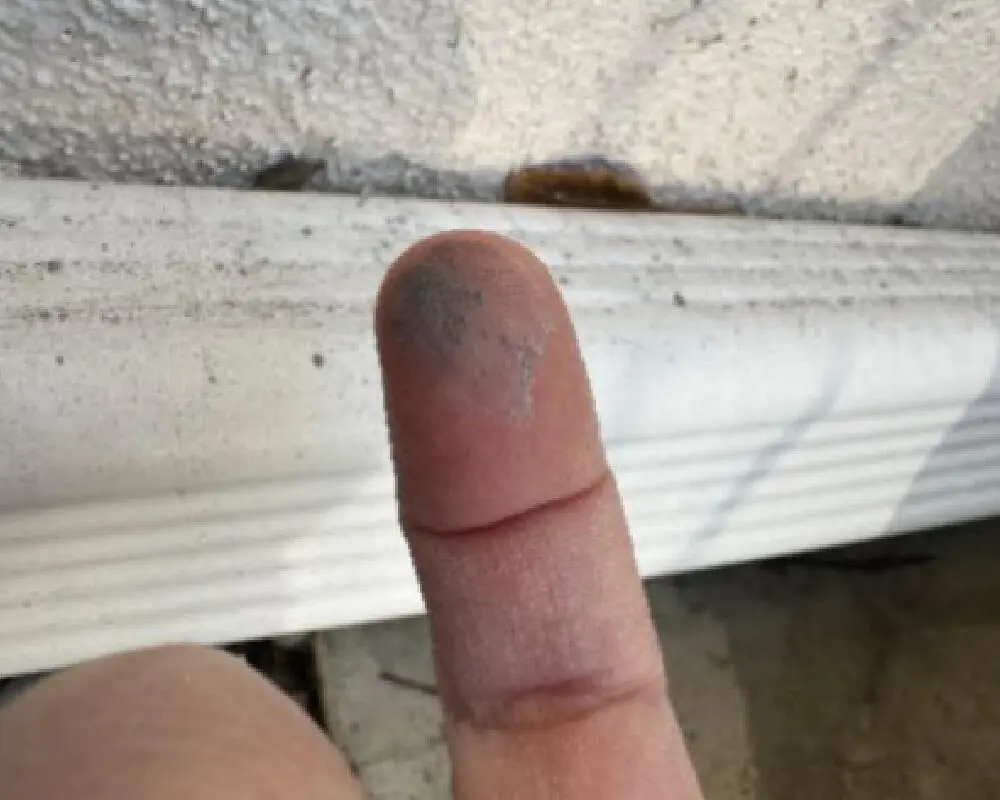
This Los Angeles-area home sat roughly five miles from the Eaton Fire, but distance didn't stop smoke and soot from contaminating building surfaces, contents, exterior components and the pool. The family also lost food in an electricity outage.
A restoration estimate, inspection photos and food-loss records were submitted. Even so, the carrier did not approve every item without a fight.
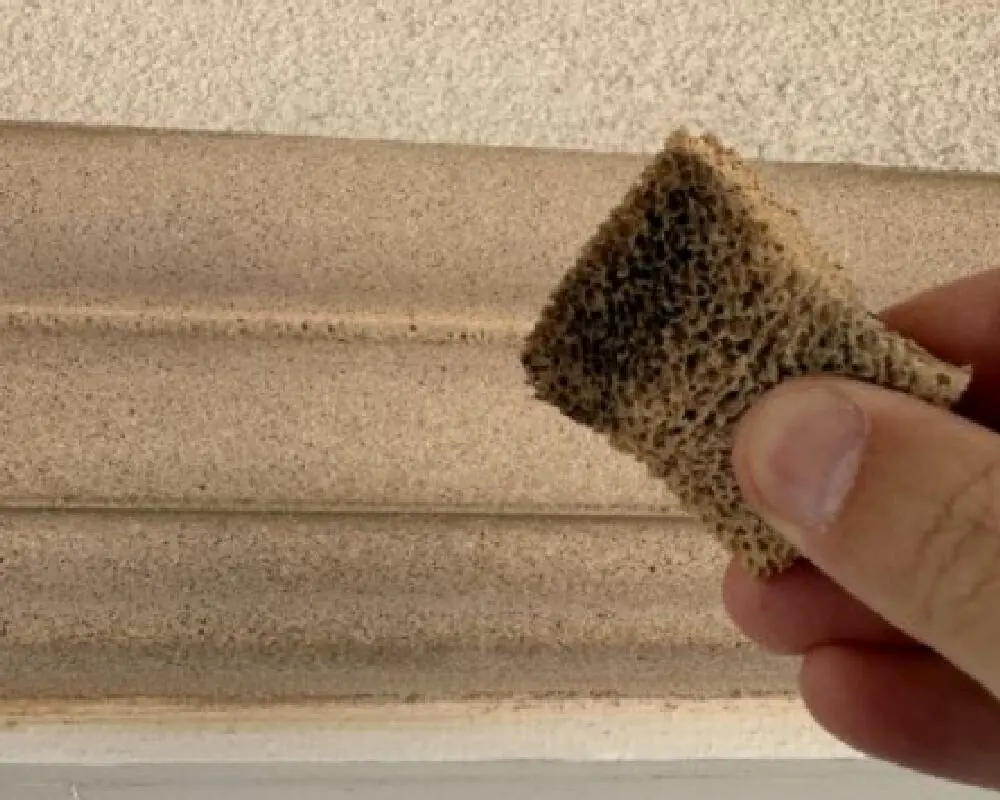
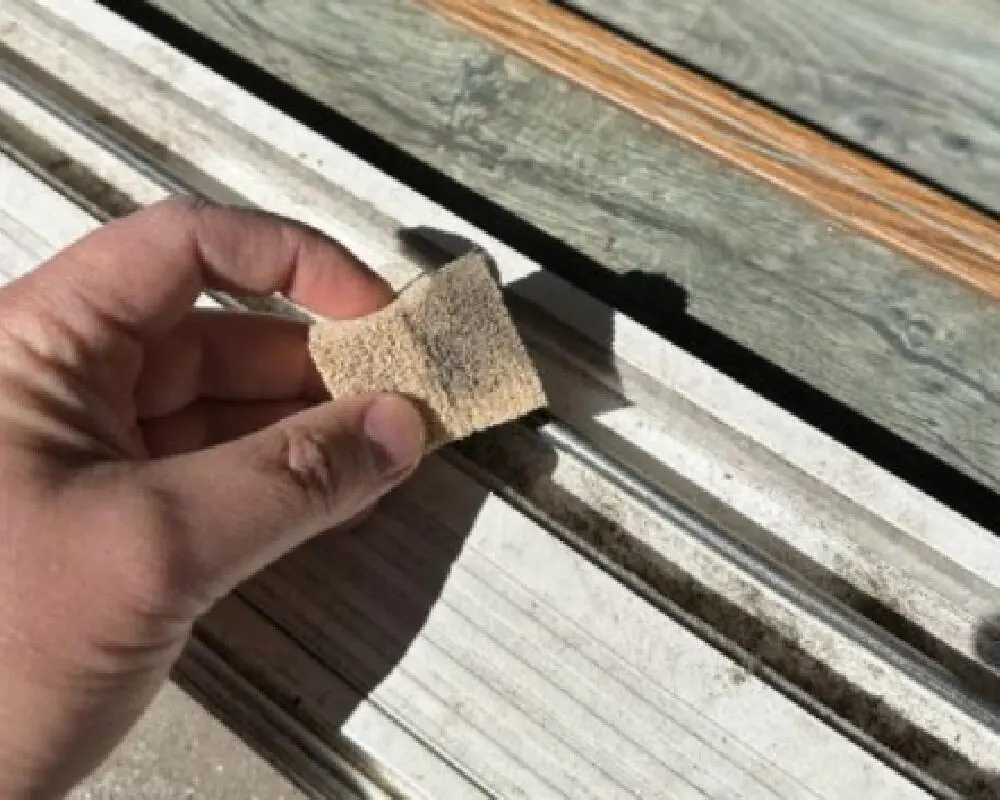
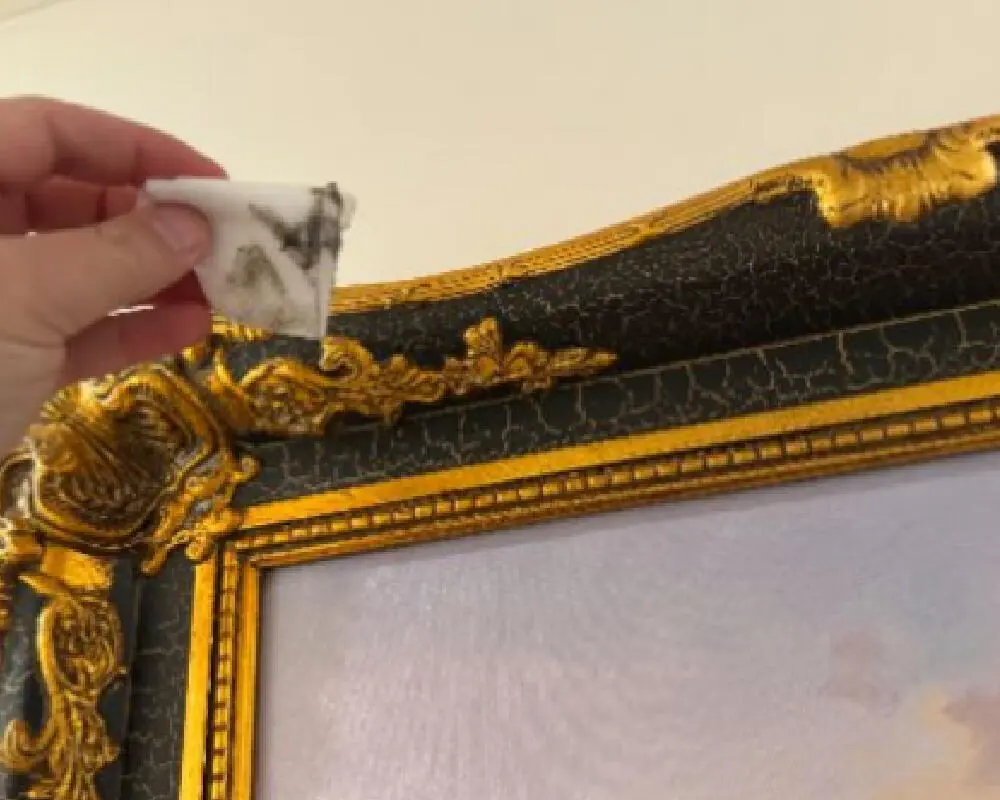
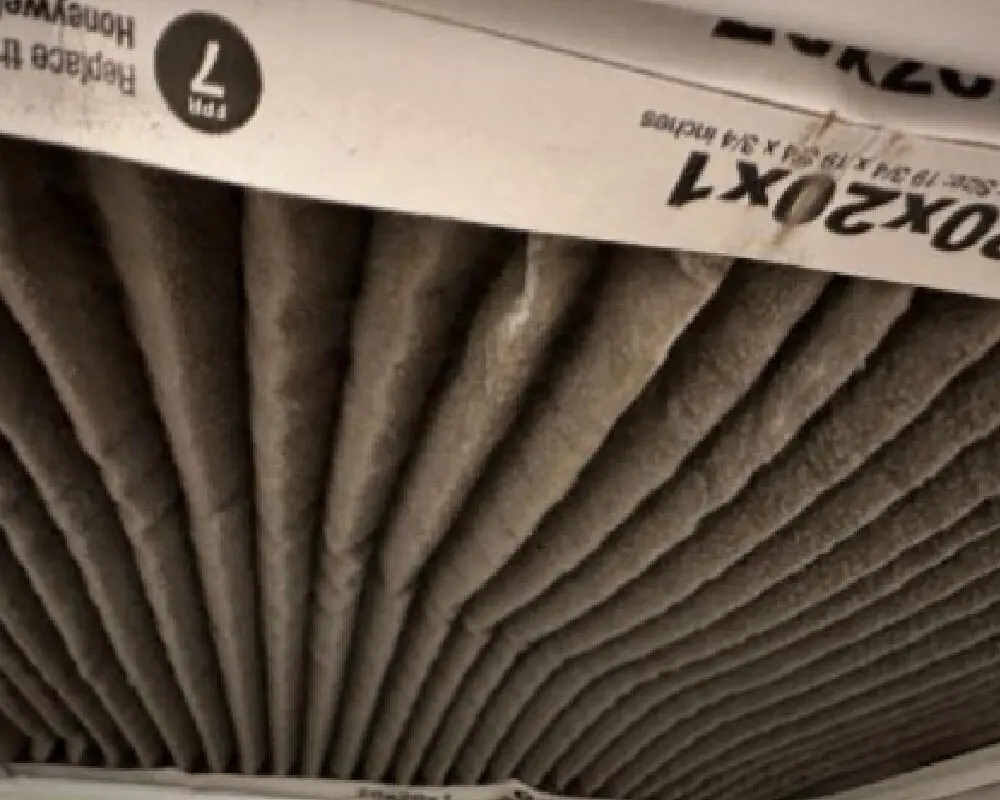
Carrier pushback
The carrier challenged several parts of the cleaning estimate:
- Changing heavy cleaning to normal cleaning
- Reducing the exterior and roof cleaning scope
- Objecting to pressure washing over possible damage to the roof or exterior
- Removing attic sealing and stain-blocking items
- Removing hydroxyl generator charges
- Asking for more proof of food spoilage
Our approach
We submitted the restoration estimate and photo report, followed up repeatedly while it sat under review, submitted pool cleaning as its own scope item and pursued the contents cleaning estimate until it was paid.
When the carrier objected to pressure washing the roof and exterior, we didn't drop the item. We revised the scope to manual cleaning, which kept the substance of the claim while answering the carrier's concern. Supplement negotiations continued until more dwelling cleaning money was issued.
The result
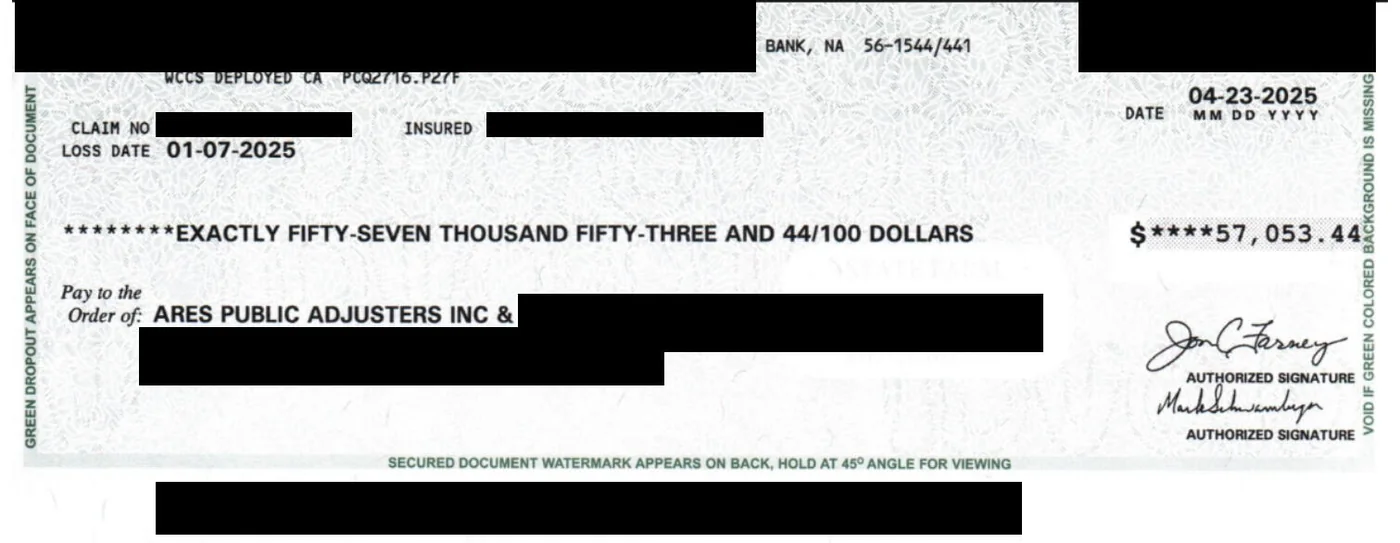
| Dwelling cleaning | $57,053.44 |
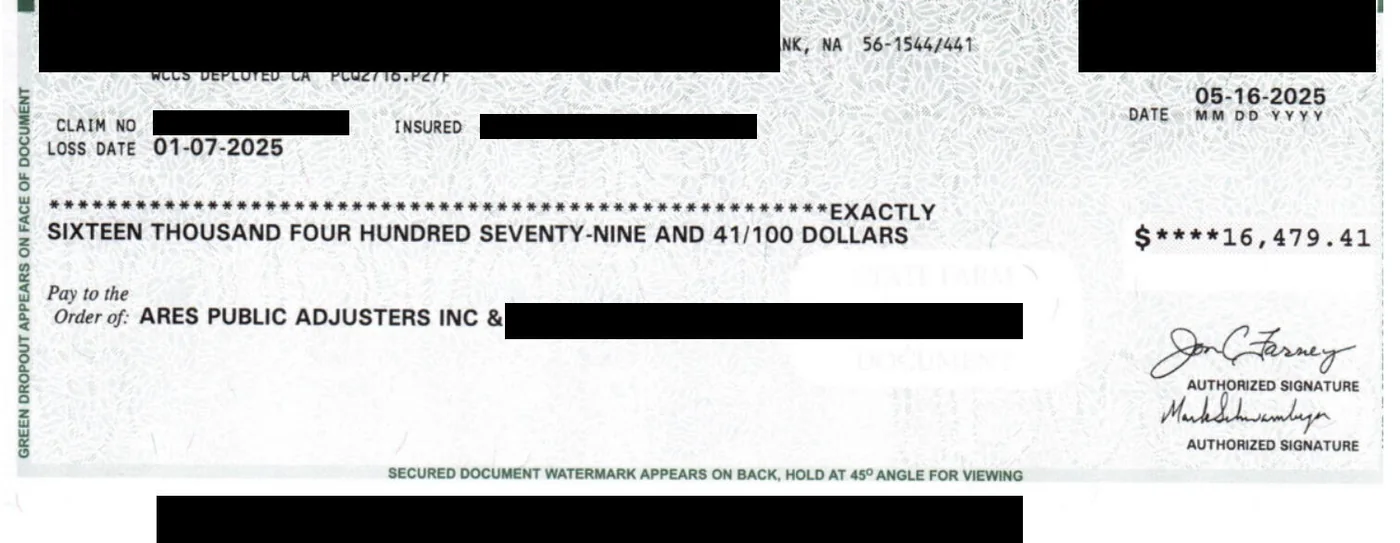
| Contents cleaning | $16,479.41 |
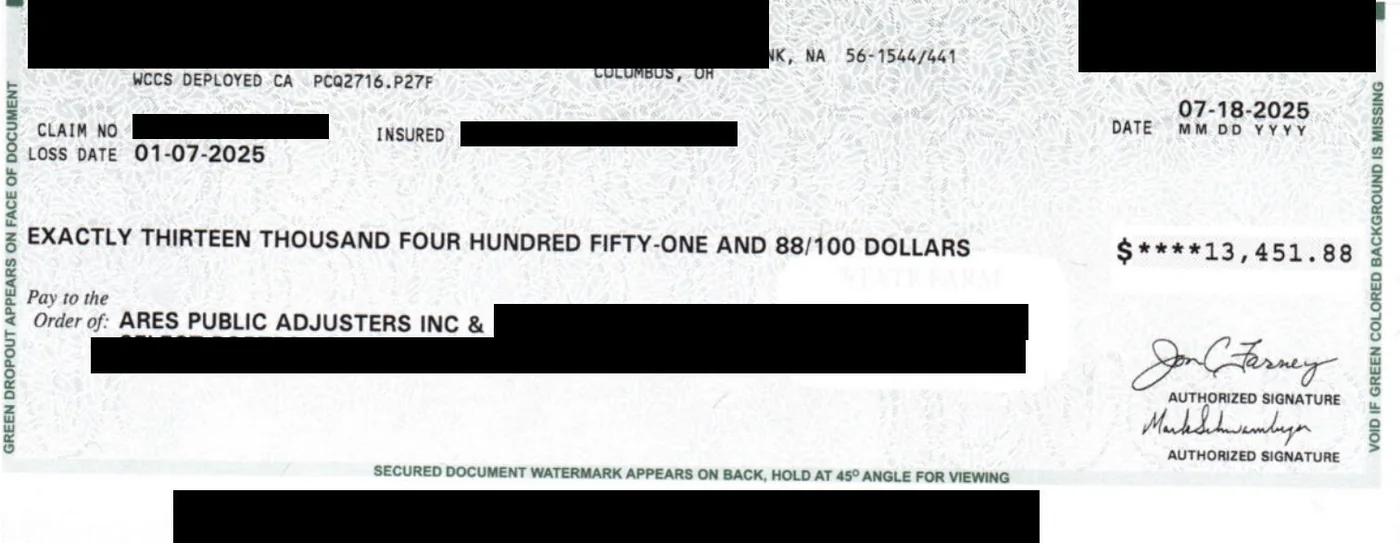
| Dwelling cleaning supplement | $13,451.88 |
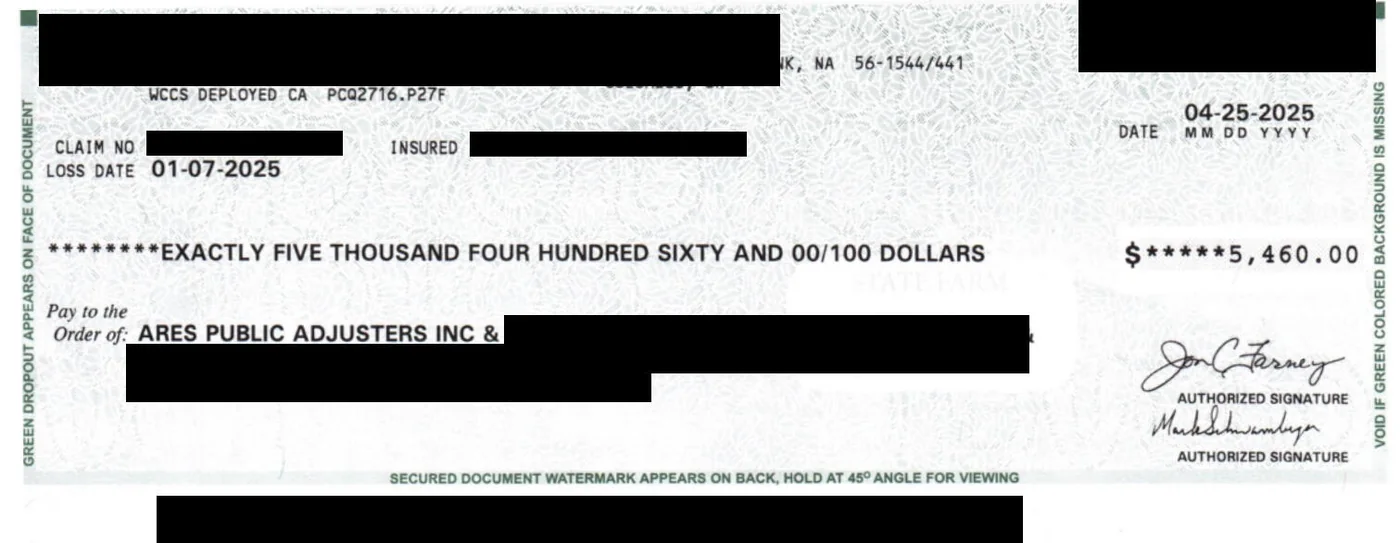
| Pool cleaning | $5,460.00 |
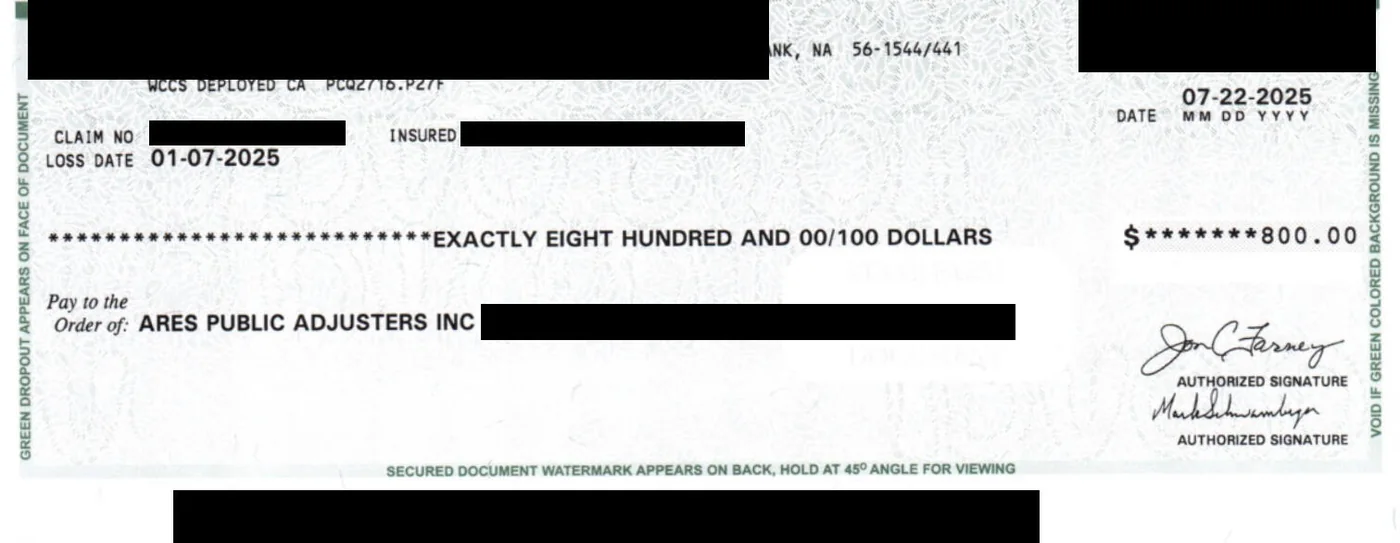
| Food spoilage from outage | $800.00 |
| Total settlement | $93,244.73 |
Why it matters
A home does not need to burn down to have a serious smoke loss. A partial payment does not mean the full claim has been valued correctly. The carrier may pay an initial cleaning amount and still dispute contents, pool cleaning, roof cleaning or supplements.
Every claim is different and no result is guaranteed.
Settlement checks