Your Sherman Oaks public adjuster
Sherman Oaks has a mix of older Valley homes, hillside properties and condos along Ventura Boulevard, and each one brings its own kind of claim. We work for you, not the insurance company. We inspect the property in person, deal with the adjuster and make sure the damage is fully documented and paid at what it really costs to repair or replace.
If your claim was denied, underpaid or delayed, or you are not sure the insurance company's number makes sense, call us before you agree to a settlement or sign anything.
What shapes insurance claims in Sherman Oaks
The hills along Mulholland Drive bring wildfire exposure and Santa Ana winds, and heavy winter rain can cause drainage and slope problems on hillside lots. In the flats, most claims are water, roof and smoke losses.
Much of Sherman Oaks was built decades ago. Older supply lines, drain lines and water heaters fail, and many condos and apartments near Ventura Boulevard share walls, floors and ceilings, so one leak can affect several units. Condo owners often deal with both the HOA's master policy and their own.
The Valley's summer heat and Santa Ana wind events are hard on roofs, and smoke from fires elsewhere in the region can settle in the Valley. Insurance companies often underestimate smoke in HVAC systems, ducts and attics, and partial roof repair offers are common.
Claims we handle in Sherman Oaks
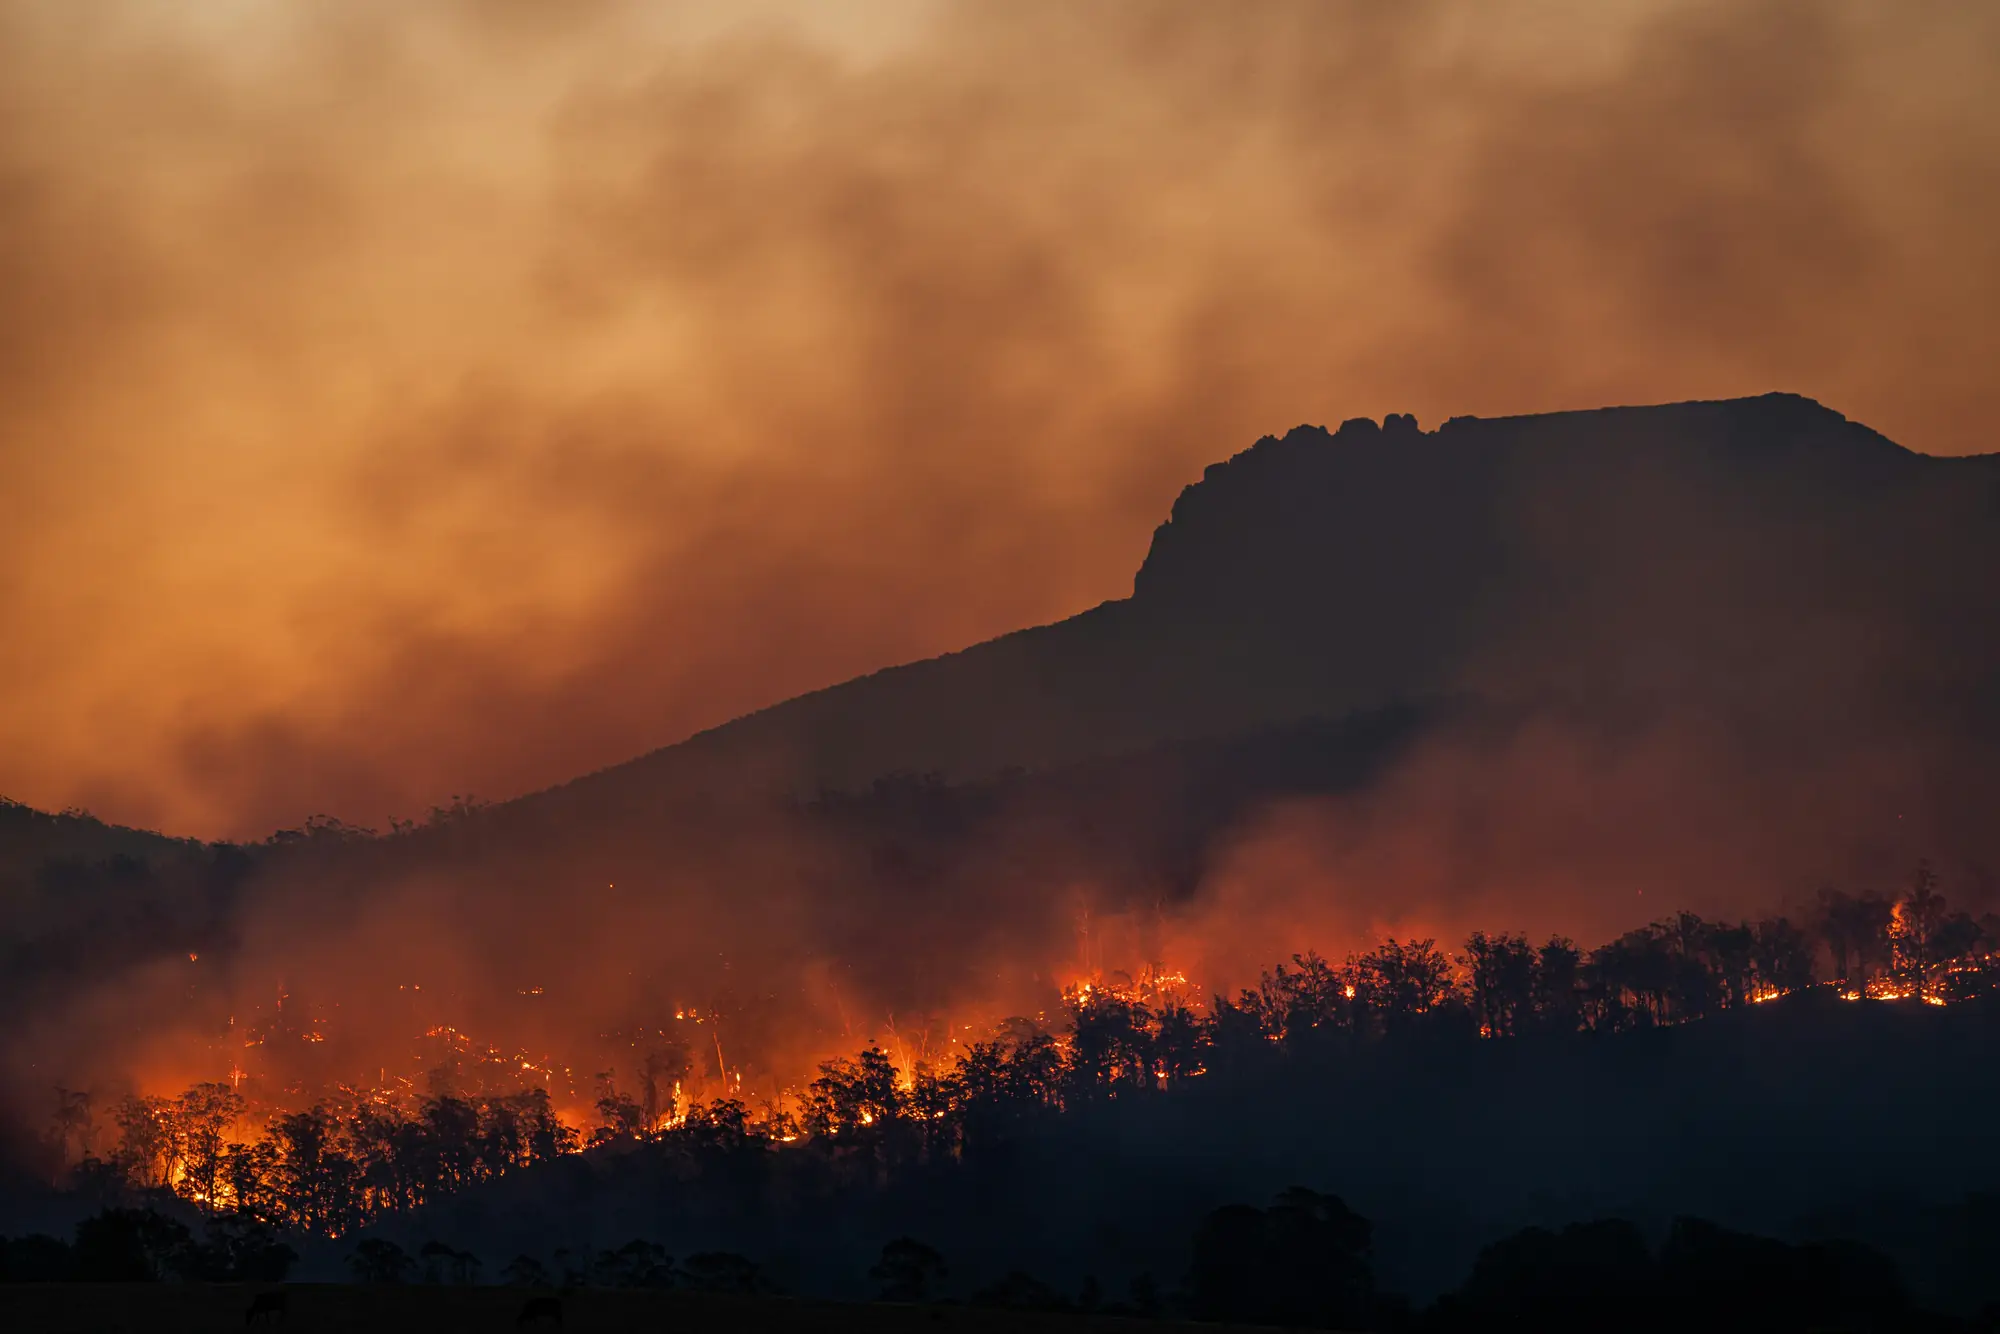
- Fire and smoke damage, including wildfire smoke and ash in homes that did not burn.
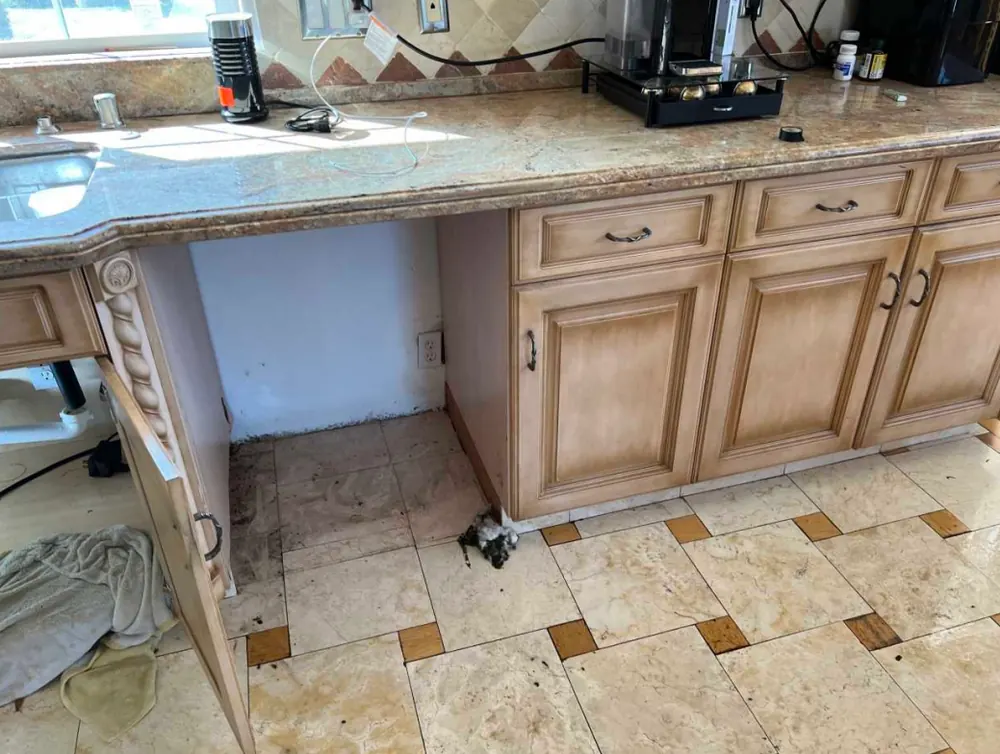
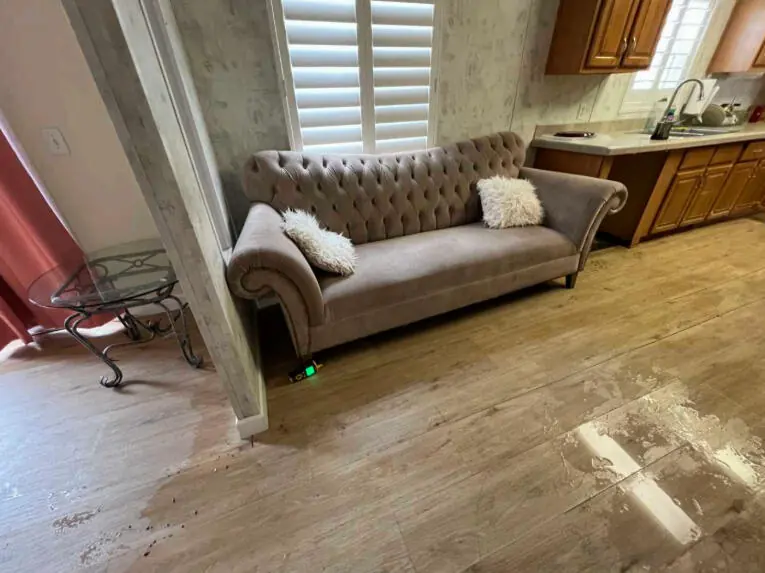
- Water damage, from burst pipes and failed supply lines to hidden leaks and mold disputes.
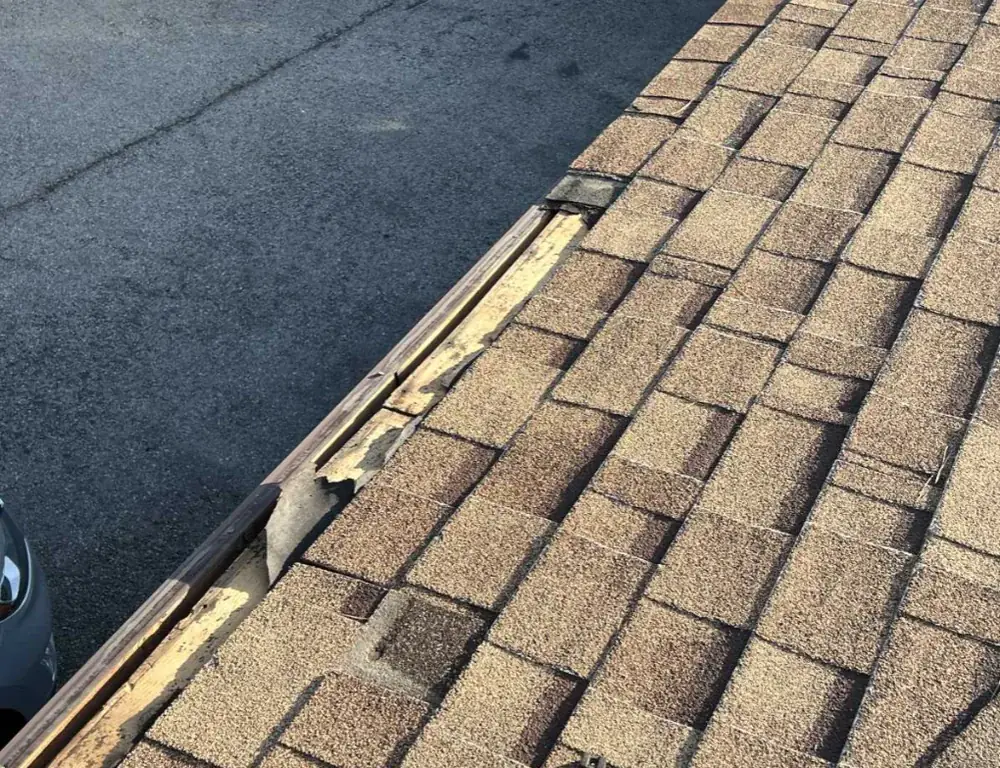
- Wind and roof damage, including partial repair offers when the whole roof needs replacing.
- Vandalism and burglary, from stolen belongings to broken doors and windows.
- Personal property and contents, so your belongings are valued fairly.
- Condo and HOA claims, where the master policy and the unit owner's policy both come into play.
How it works
- Free claim review. Tell us what happened. We look at your policy and the insurance company's position and tell you where you stand.
- Documentation. We inspect the property, document the damage and prepare a detailed estimate and photo report.
- Negotiation. We deal with the adjuster, respond to their estimate and push back on anything that was left out or undervalued.
- Appraisal if needed. When the two sides cannot agree, we can invoke the appraisal clause in your policy.
Public adjusters are paid a percentage of the amount recovered, and the fee is spelled out in a written contract before you sign anything.
Serving Sherman Oaks and nearby areas
We work with property owners across Sherman Oaks, including the hills near Mulholland Drive, the streets north and south of Ventura Boulevard and the areas near Van Nuys Boulevard. We also help clients in Los Angeles, North Hollywood, Burbank and Beverly Hills and across Los Angeles County.
Our office is at 414 N Orange St, Unit 107, Glendale, CA 91203. Get directions.